Rates at a glance
| Work or supply | Rate |
|---|---|
| Conversion work that splits a house into a larger number of dwellings | 5% |
| Conversion work that merges flats or houses into fewer dwellings | 5% |
| Building materials supplied and fitted by the contractor | 5% |
| Refurbishing a lived-in house or flat where the number of dwellings stays the same | 20% |
| Carpets, appliances and fitted furniture other than kitchens | 20% |
| Architects', surveyors' and consultants' fees | 20% |
The rate for your project depends on its facts. Each line of a quote is rated on its own.
Does yours qualify?
The headline tests. All of them have to hold.
- The building contains a different number of dwellings after the work than before.
- The number can go up or down, so splitting one house into flats and merging flats into one house both count.
- Each resulting unit is a self-contained home that can be used on its own.
Plus 3 further points we test. These are the ones that are easy to miss, and any one of them can change the answer. A qualification report works through every one against your documents.
About the qualification reportWhere projects go wrong
- The same number before and after. Refurbishing four flats that stay four flats is 20%, unless they have been empty for two years.
- Treating excluded items as building materials. Carpets, appliances and fitted wardrobes stay at 20%.
We check for 4 more pitfalls on every project of this kind. Most only come to light once the work has been invoiced, which is the expensive time to find them.
What it can be worth
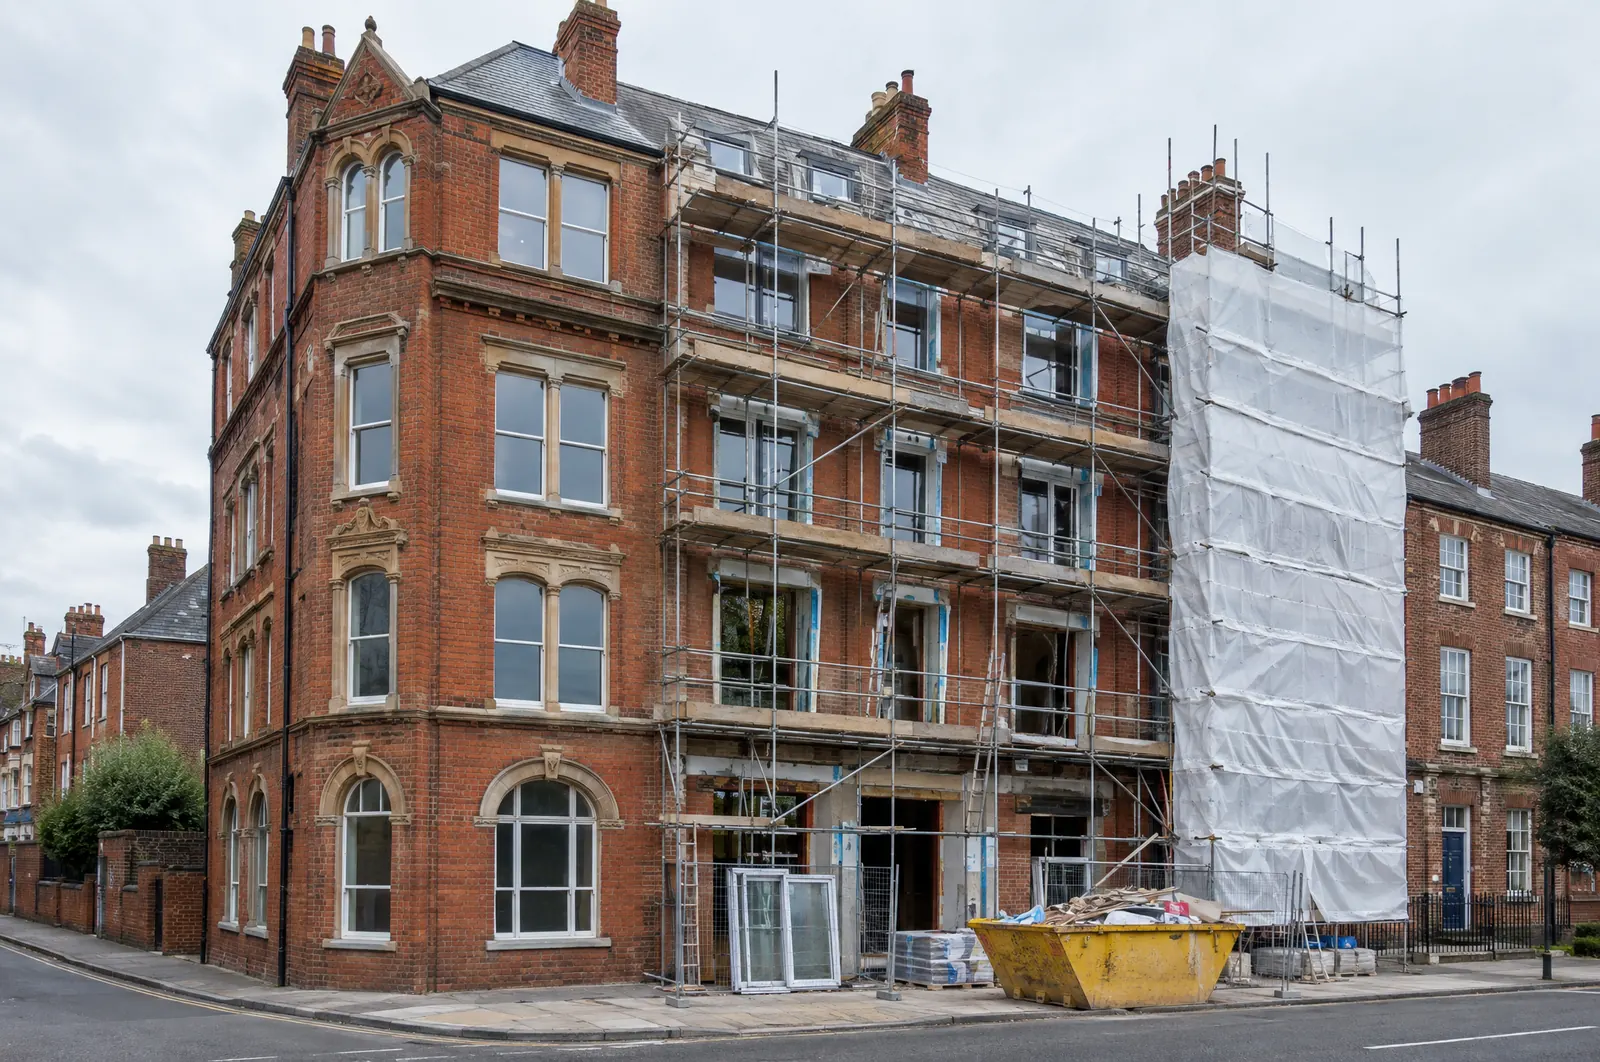
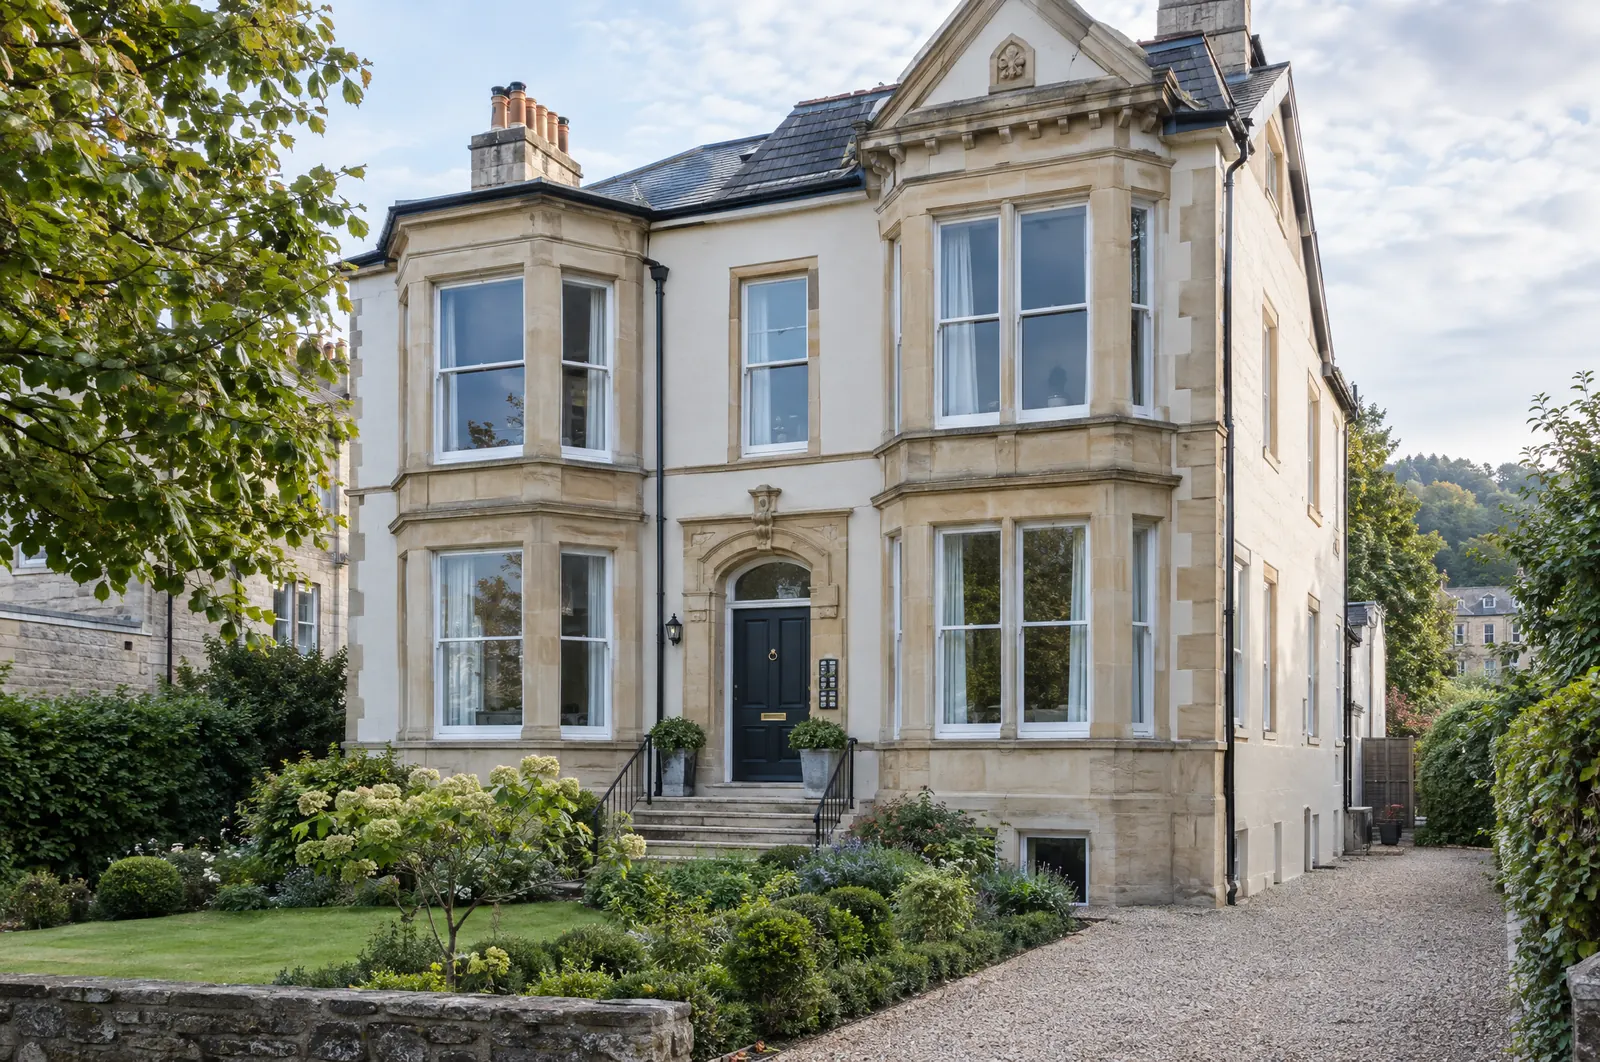
A Victorian house split into four flats
A builder quotes £310,000 before VAT to convert a large terraced house, lived in until the sale, into four self-contained flats. The quote shows 20% throughout, on the basis that the house was never empty.
| Item | Net | Rate | VAT |
|---|---|---|---|
| Structural alterations and new entrances | £62,000 | 5% | £3,100 |
| Partitions, fire separation and soundproofing | £71,000 | 5% | £3,550 |
| Plumbing, heating and electrics for four flats | £79,000 | 5% | £3,950 |
| Four fitted kitchens, units and worktops | £32,000 | 5% | £1,600 |
| Four bathrooms | £26,000 | 5% | £1,300 |
| Plastering, joinery and decoration | £22,000 | 5% | £1,100 |
| Kitchen appliances | £9,000 | 20% | £1,800 |
| Carpets | £6,000 | 20% | £1,200 |
| Fitted wardrobes | £3,000 | 20% | £600 |
| Total | £310,000 | £18,200 |
- VAT if quoted at 20% throughout
- £62,000
- VAT rated line by line
- £18,200
- Difference
- £43,800
An example to show how the rates fall when the number of dwellings changes. It is not a figure for your project.
How we help with converting a house into flats
We establish whether your project changes the number of dwellings in the way the reduced rate needs. You get a clear answer on whether it qualifies, with the reasoning written down so the builder can see the basis for the rate and your accountant can check it. If the right rate is 20%, that is the answer you get.
A line-by-line analysis then gives you the right rate for every part of the quote and a letter for your builder setting out what to charge. Many of these jobs are quoted at 20% because the house was never empty, but that is not a condition of this relief. Our guide to the changed number of dwellings rule gives the background. To start, send us your quote.
Questions
What is the VAT on converting a house into flats?
It is 5% where the conversion changes the number of dwellings and each flat is a self-contained single household dwelling. The rate covers the contractor's labour and the building materials they supply and fit. Carpets, appliances and fitted furniture other than kitchens are 20%.
Does the house need to have been empty for two years to get 5% VAT?
No. The two-year rule is a separate relief for renovating empty homes. A conversion that changes the number of dwellings qualifies on its own terms, even if the house was lived in until the builders arrived.
Is knocking two flats into one house charged at 5% VAT?
It can be. The rule is about the number changing, not rising. Two flats merged into one house takes the count from two to one, and one is enough to meet the condition that at least one dwelling remains.
Based on the Value Added Tax Act 1994 and HMRC's published guidance. This page explains how the rules work in general. It is not advice on your project, and no rate applies until the facts have been analysed.