Rates at a glance
| Work or supply | Rate |
|---|---|
| Approved alterations to a listed building | 20% |
| Repair and maintenance of a listed building | 20% |
| Extensions, and architects' and consultants' fees | 20% |
| A qualifying conversion, or the renovation of a listed home empty for two years | 5% |
| Installing energy-saving materials until 31 March 2027, or specified adaptations for a disabled person | 0% |
| First sale or long lease of a substantially reconstructed listed building | 0% |
The rate for your project depends on its facts. Each line of a quote is rated on its own.
When a lower rate can still apply
Most of this work is 20%. These are the exceptions worth checking.
- The work is a qualifying conversion, such as a listed barn turned into a house or a listed house split into flats.
- The building is a home that has not been lived in during the two years before the work starts.
- The work is the installation of qualifying energy-saving materials in residential accommodation.
Plus 2 further points we test. These are the ones that are easy to miss, and any one of them can change the answer. A qualification report works through every one against your documents.
About the qualification reportWhere projects go wrong
- Assuming that listing brings a relief. It does not, and a listed building is tested in the same way as any other.
- Pricing from pre-2012 precedent. Old specifications and rates that assume zero-rated alterations are now wrong, and the difference is the full 20%.
We check for 4 more pitfalls on every project of this kind. Most only come to light once the work has been invoiced, which is the expensive time to find them.
What it can be worth
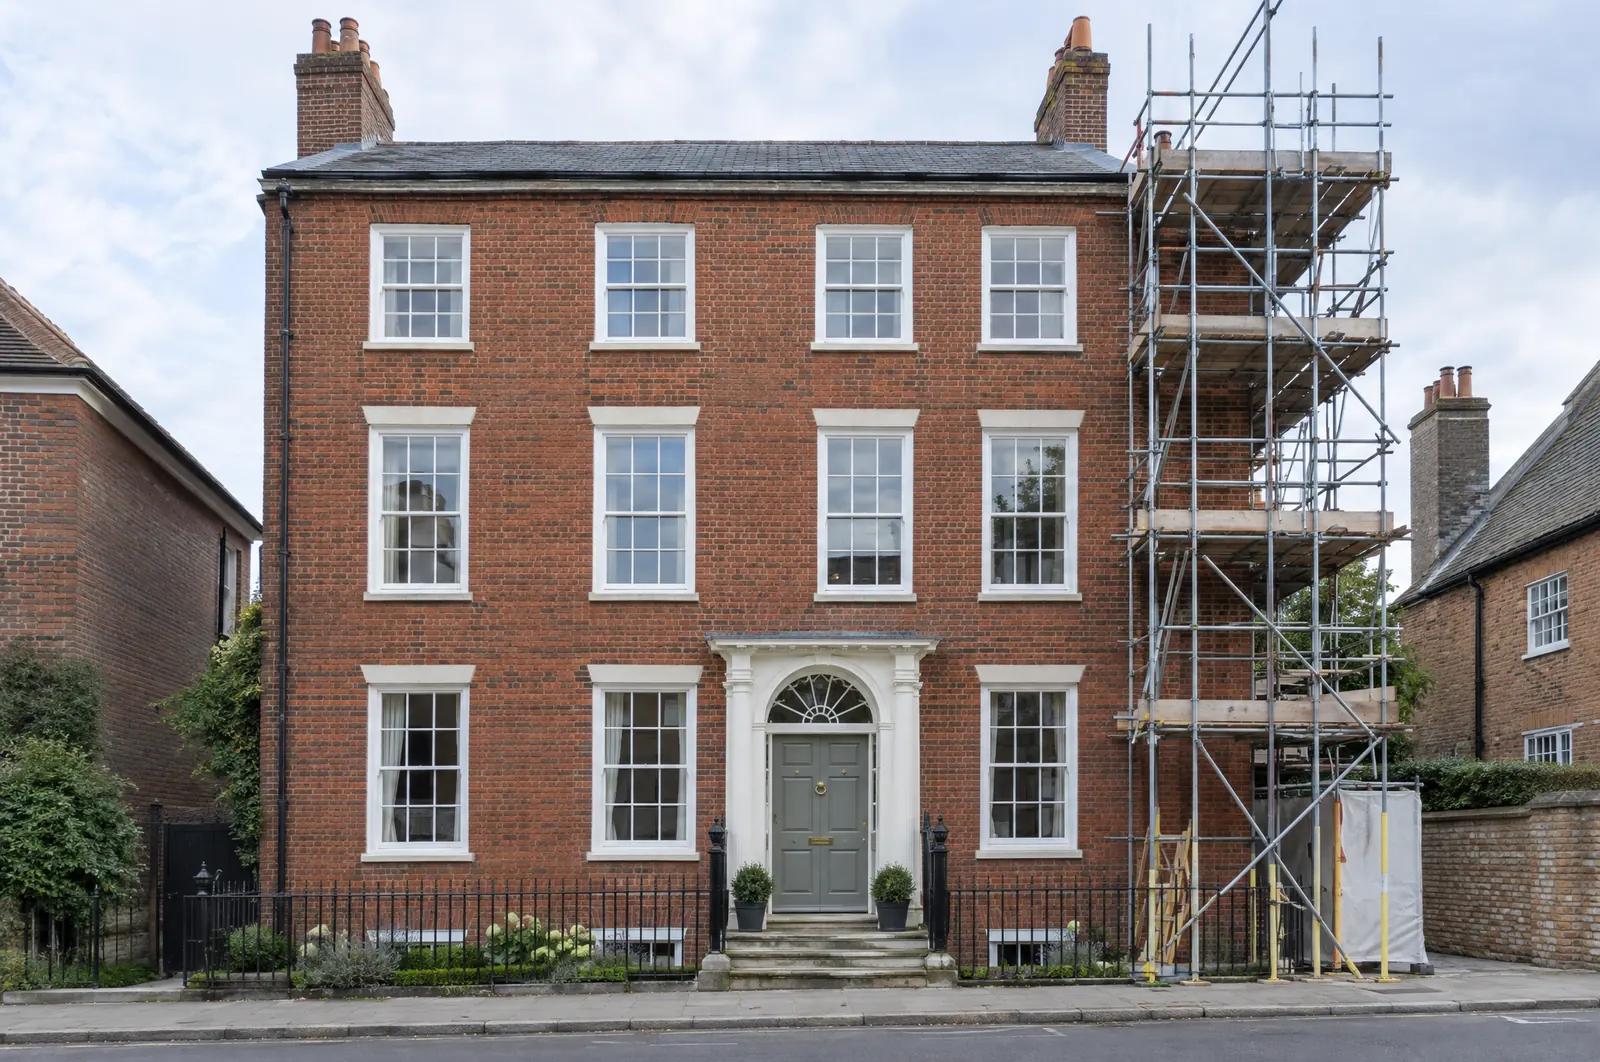
Works to an occupied Grade II listed house
The owners of a Grade II listed farmhouse they live in receive a quote of £230,000 before VAT. An older quote for a neighbour's house, from before 2012, had shown the alterations at 0%.
| Item | Net | Rate | VAT |
|---|---|---|---|
| Internal alterations under listed building consent | £68,000 | 20% | £13,600 |
| Re-roofing in natural slate, with leadwork | £54,000 | 20% | £10,800 |
| Lime plaster and stonework repairs | £37,000 | 20% | £7,400 |
| Rewiring and plumbing | £28,000 | 20% | £5,600 |
| Sash window repairs | £22,000 | 20% | £4,400 |
| Carpets | £3,000 | 20% | £600 |
| Air source heat pump, supplied and installed | £14,000 | 0% | £0 |
| Loft insulation, supplied and installed | £4,000 | 0% | £0 |
| Total | £230,000 | £42,400 |
- VAT if quoted at 20% throughout
- £46,000
- VAT rated line by line
- £42,400
- Difference
- £3,600
An example to show how the rates fall on a typical listed building project in 2026. The heat pump and insulation are separate installations of energy-saving materials. It is not a figure for your project.
How we help with listed building projects
For most work on a listed building the answer is 20%, and we will tell you that plainly. What we establish is whether the building's history or the project itself brings one of the general reliefs into play, and for which parts of the job. You get a clear answer on whether any of it qualifies, with the reasoning written down for your builder.
Where there is something to analyse, a line-by-line analysis gives you the right rate for each part of the quote and a letter for your builder. Older specifications and quotes often still follow the rules from before 2012, so a fresh check is worth having. Our guide to the 2012 change has the background. To start, send us your quote.
Questions
Is VAT charged on work to listed buildings?
Yes, at 20% in most cases. Alterations, repairs, maintenance and extensions to a listed building are all standard rated. A lower rate applies only where the project meets the conditions of a relief that is open to any building, listed or not.
Are alterations to a listed building still zero rated?
No. The zero rate for approved alterations to protected buildings was withdrawn on 1 October 2012, and approved alterations have been 20% since then. Any advice, quote or specification that still assumes 0% is out of date.
Can I get 5% VAT on a listed building?
Not because it is listed. The 5% rate can apply where the work is a qualifying conversion, for example a listed barn into a house, or where the building is a home that has been empty for two years before the work starts. Those rules are the same for listed and unlisted buildings.
Based on the Value Added Tax Act 1994 and HMRC's published guidance. This page explains how the rules work in general. It is not advice on your project, and no rate applies until the facts have been analysed.